How to Lower Your Monthly Mortgage Payment (Without the 30-Year Reset Trap)
If opening your monthly mortgage statement makes your stomach turn, you are not alone. Most homeowners overpay by hundreds of dollars every single month simply because big banks make refinancing sound like a dangerous legal nightmare. In this guide, I will show you how to cut through the banking myths, run the real break-even math on closing fees, and lower your interest rate without resetting your loan clock for another thirty years.
📌 Fast Facts: How to Fix Your Mortgage Without Getting Burned
- You do not need an 800 credit score: Government-backed and conventional streamlined programs often approve rate drops for everyday credit profiles.
- No cash out of pocket: Most lenders roll administrative fees straight into the loan balance—just make sure your break-even timeline is under 24 months.
- Never reset your clock blindly: Do not sign another 30-year note if you are already years in; request a custom 25- or 20-year term to save tens of thousands in interest.
- Shop at least three lenders: Comparing official Loan Estimate forms from a credit union, a digital broker, and a bank can instantly save you thousands in junk fees.
Pulling Back the Curtain on Home Loan Fiction
To understand why we stay stuck in bad financial deals, we have to look at how banks design their contracts. When you sit down at a closing table for the first time, everything feels like a sacred, unbreakable oath.
There are stacks of papers, official stamps, and serious-looking people in suits telling you where to sign. It is completely normal to walk away from that experience feeling like your mortgage is carved in stone.
The banking industry relies heavily on this psychological intimidation. If they can make you believe that modifying your loan is too complicated, too risky, or too expensive, you will never bother them to ask for a lower rate.
They get to keep collecting high interest from you month after month, year after year. It is a brilliant business model for them, but a terrible deal for your personal family savings account.
Let us systematically dismantle the most expensive lies you have been told about changing your home loan. Once you see through the smoke and mirrors, you will realize how much power you actually hold as a consumer.
The Great Misconception About Credit Perfection
Let us start with the biggest boogeyman in the entire financial closet: the obsession with having an immaculate credit history. You have probably been told that unless your credit score looks like a pristine mountain peak, you cannot even dream of touching your mortgage.
People assume that a single missed credit card payment from years ago will cause a bank loan officer to slam the door right in their face. This specific fear keeps millions of homeowners locked in high-rate contracts.
The reality on the street is completely different. While having a high credit score certainly unlocks the absolute best promotional rates, you do not need perfection to see massive savings.
Federal backing programs and streamlined refinancing options are specifically built to accommodate average, everyday financial profiles. Lenders are operating in a competitive market, and they want your business.
If your current rate is sitting far above the current market average, a bank would much rather capture your reliable monthly payment at a slightly lower rate than lose you to a competitor. I let my own fear of an imperfect credit score delay my financial progress for over a year.
When I finally swallowed my pride and spoke to an independent professional, I learned that my score was more than enough to qualify for a substantial rate drop. I had let a phantom limitation steal thousands of dollars out of my future pocket.
🎙️ Reality Check from Dave Ramsey: Does Refinancing Make Sense for You?
If you are carrying credit cards or auto loans alongside a heavy mortgage, you might wonder if modifying your home loan is the right move. Check out this no-nonsense advice from financial expert Dave Ramsey. He explains whether refinancing actually solves your cash-flow problems or just shuffles your debt around:
The Closing Cost Scare Factor
Another major reason people refuse to look at their mortgage is the terrifying memory of closing costs. Everyone remembers draining their bank account to pay thousands of dollars in fees on the day they bought their house.
Because of this painful memory, homeowners assume that modifying their loan will require another massive, upfront cash sacrifice. They think they need to write a ten-thousand-dollar check just to get a lower monthly bill.
This is a complete misunderstanding of modern lending options. Lenders know that asking for thousands of dollars in cash upfront is a dealbreaker for most working families.
To solve this, they offer what the industry calls a "zero-out-of-pocket" or rolled-in cost structure. The administrative fees required to draw up the new contract are simply added directly onto your total loan balance.
If your remaining balance is two hundred and fifty thousand dollars, and the processing fees come out to four thousand, your new loan is simply written for two hundred and fifty-four thousand dollars. No cash leaves your bank account on signing day.
The secret is calculating your exact "break-even point." This is the simple math problem that tells you how many months of lower payments it takes to completely pay off those rolled-in fees.
If your new monthly savings equal three hundred dollars, and your rolled-in fees are three thousand, you will hit your break-even point in just ten months. If you plan on staying in your home for five more years, you clear massive profit after month ten.
🧮 My Simple Break-Even Rule: A Real $300,000 Loan Example
Let us say you owe $300,000 on your home at 6.75% interest. You find an offer to drop your rate to 5.50%:
- Your Old Payment (Principal + Interest): $1,945/month
- Your New Payment (Principal + Interest): $1,703/month
- Your Net Monthly Cash Savings: $242/month
- Total Rolled-In Closing Fees: $3,600
- Your Break-Even Formula: $3,600 ÷ $242 = 14.8 Months
The Takeaway: If you plan to live in that house for more than 15 months, doing this deal puts pure profit straight back into your pocket every single month after month 15.
The Endless Thirty-Year Loop Myth
Here is a psychological trap that catches many cautious homeowners off guard. Your well-meaning neighbor might pull you aside and warn you that changing your loan resets the clock, forcing you into another endless thirty-year debt sentence.
It sounds completely logical on the surface. If you sign a new thirty-year contract, the mathematical timeline starts all over again from day one.
However, this myth completely ignores the incredible flexibility built into modern mortgage contracts. You are never legally forced to accept a full thirty-year term when you restructure your debt.
If you have already paid off four years of your original mortgage, you can instruct your lender to write your new contract for a twenty-six-year term. You can even choose a twenty-year or a fifteen-year schedule.
By matching your new, lower rate to a shorter timeline, you can actually crush your total debt much faster than your original plan. You dictate the timeline based on your personal retirement goals, not some rigid corporate template.
Why You Should Demand a "Custom Term" (Real Numbers)
Underwriter Tip: Never let a loan officer default your paperwork to 360 months if you are already years into your mortgage. Tell them up front: "Write my new contract to match my remaining payoff timeline."
The Dreaded White-Glove Appraisal Fear
Many people put off looking at their mortgage because they are convinced an appraiser is going to inspect their house like a harsh military general. They worry that a cluttered living room or an unpainted fence will somehow tank their refinancing application.
They spend weeks and hundreds of dollars frantically trying to remodel rooms just to impress a bank worker. This creates a massive barrier of entry in their own minds.
Appraisers are not looking at your interior design choices, your family photos, or whether your bed is made. They are purely focused on the structural scale and the recent market value of similar homes in your immediate zip code.
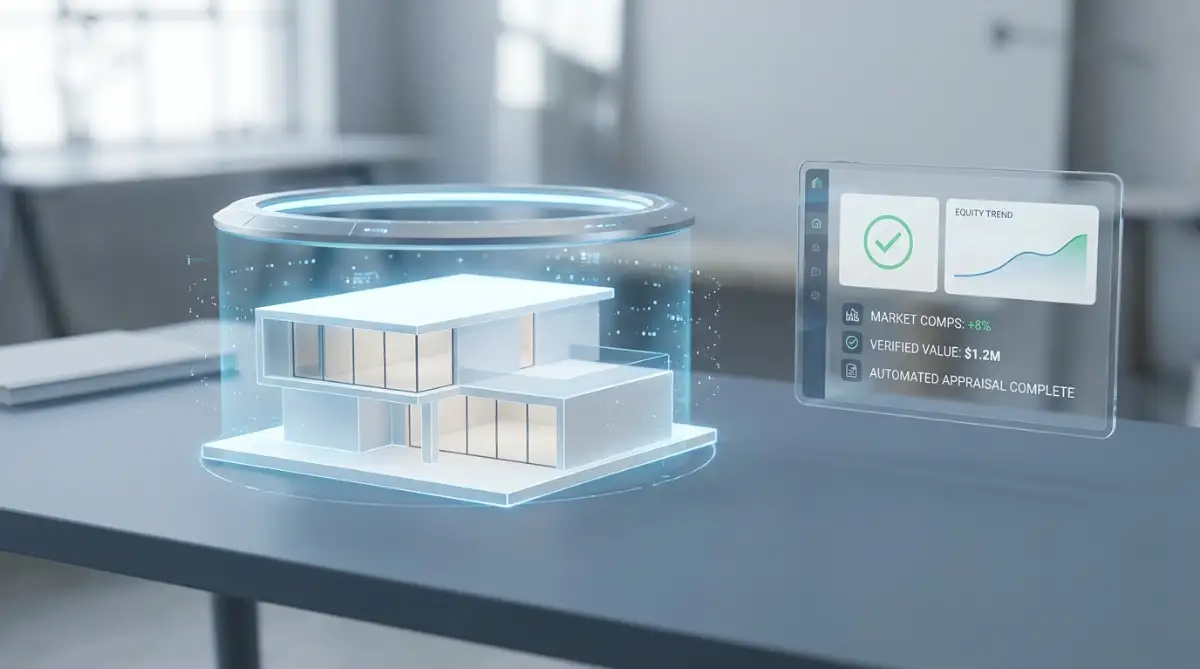
Furthermore, the entire appraisal process has evolved dramatically with digital technology. Thanks to massive real estate databases, many modern lenders rely heavily on automated valuation models that look at local data instantly.
You can often complete the entire property evaluation process without a single stranger walking through your front door or judging your housekeeping.
The Loyalty Trap
We are taught from a young age that loyalty to an institution is a supreme virtue. We keep our checking accounts at the same local bank for decades because we trust the friendly teller who knows our name.
This deep sense of loyalty is perhaps the most expensive mistake you can make in the housing market. Your local bank branch manager has zero control over national interest rates or automated underwriting algorithms.
Massive financial institutions often rely on your sense of comfortable loyalty to keep you paying high rates. They know you are too busy to shop around, so they quietly leave you sitting in an expensive contract.
If you want a genuinely good deal, you have to treat your mortgage like a serious business transaction. Shopping around across multiple independent lenders forces them to compete for your business, driving your costs down significantly.
Smart Strategies to Master Your Home Loan Long-Term
Now that we have smashed through the terrifying myths keeping your budget locked down, it is time to build a smart roadmap for your financial future. Changing your mortgage terms successfully is not just a one-time event. It requires a calm, calculated approach to managing your household debt over many years.
You cannot simply sign a new contract and then completely forget about your personal finances. True financial freedom comes from pairing a lower interest rate with consistent, intelligent daily habits.
Let us explore the advanced, insider strategies that smart homeowners use to stay ahead of the banking system. These professional tips will ensure you keep compounding your savings long after the ink on your new paperwork has dried.
Timing the Market Without Going Crazy
Trying to guess the exact moment interest rates will hit their lowest point is a losing battle. Even professional Wall Street analysts with supercomputers get the timing wrong every single week.
Instead of waiting for a magical historical bottom, focus entirely on your own personal math. If the current market rate allows you to drop your monthly payment by a margin that makes your life easier today, the right time to act is right now.
According to data published by the Federal Reserve Bank of St. Louis, holding out for a fractional drop often costs homeowners more in high monthly payments than they would ever save by waiting. Take the guaranteed win in front of you instead of gambling your family budget on unpredictable market trends.
The Power of Bi-Weekly Payments
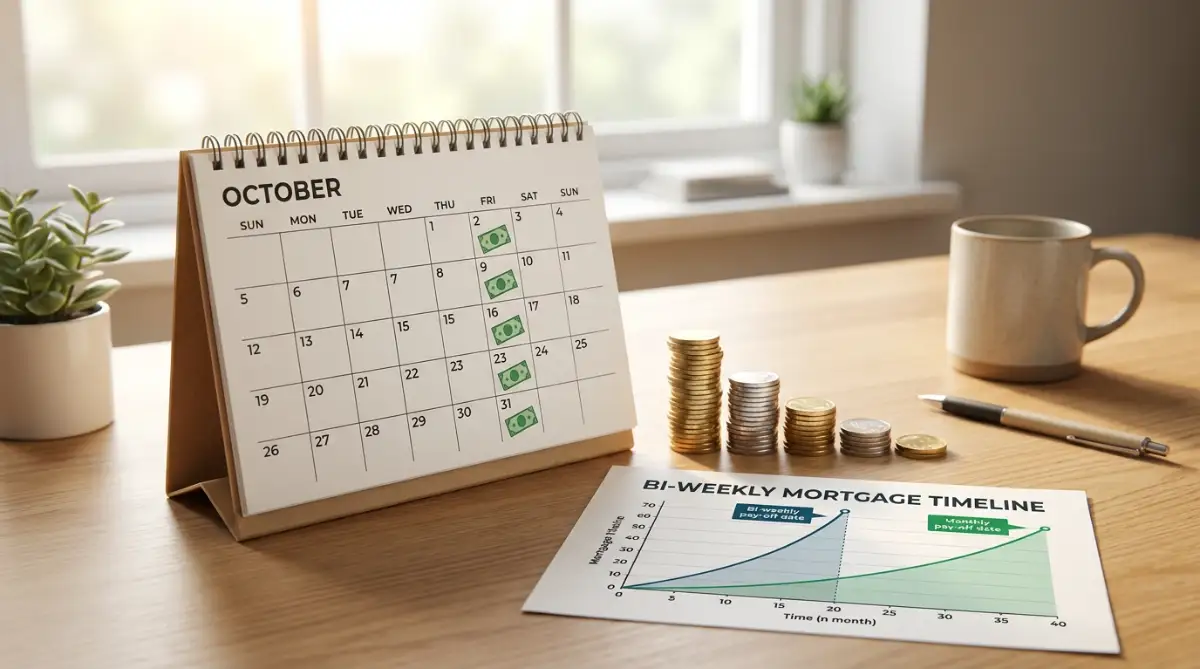
One of the most powerful pro-level secrets used by seasoned real estate investors is the bi-weekly payment schedule. Instead of making one large mortgage payment every single month, you divide your normal payment in half and pay that amount every two weeks.
Because there are fifty-two weeks in a year, paying every two weeks means you end up making twenty-six half-payments. That equals thirteen full monthly payments every year instead of the traditional twelve.
This extra payment goes straight toward knocking down your principal balance without you even noticing the pinch. Over the lifetime of a thirty-year loan, this single habit can shave up to six or seven years off your timeline.
Just make sure you check with your lender first to ensure they apply those bi-weekly funds directly to the principal balance immediately. If you need to organize your digital banking schedule to handle this efficiently, keeping your accounts secure is a top priority, much like avoiding dangerous password management mistakes that expose your money to cyber threats.
Shopping Multiple Lenders Simultaneously
Never settle for the very first quote a bank throws your way. The modern mortgage industry is fiercely competitive, and you should make lenders fight hard to win your business.
When you decide to restructure your home loan, you should reach out to at least three different institutions. This includes your local credit union, an online digital broker, and a major national retail bank.
When you get competing Loan Estimate forms from each lender, put them side by side on your kitchen table. You will often find that one bank is charging hundreds of dollars less in administrative processing fees than the others.
You can take the lower estimate back to your favorite lender and ask them to match or beat it. According to consumer guides provided by the Consumer Financial Protection Bureau (CFPB), shopping around for your mortgage can easily save you thousands of dollars in closing fees alone.
Protecting Your Financial Infrastructure
When you are deep in the paperwork phase of managing your property loan, your digital life needs to be completely locked down. You will be sharing tax returns, Social Security numbers, and bank statements back and forth over email or secure portals.
If your home network is unsecured, you leave yourself wide open to identity theft during a very vulnerable financial transition. Before you upload sensitive documents, make sure you are using secure connections and handling your devices safely.
Sometimes people get so stressed out by financial paperwork that they ignore basic tech upkeep, such as failing to clear temporary data, or struggling with sluggish devices where you simply need to speed up your phone with simple steps to clear app cache on android. Keep your digital workspace clean, fast, and completely secure so your loan process goes smoothly without data leaks.
Financial Traps That Destroy Your New Loan Deal
Even when you follow the best advice and secure a fantastic new interest rate, the journey is still filled with unexpected hidden hazards. Human beings love to sabotage their own success right at the finish line by making careless, emotional mistakes.
If you do not stay vigilant during and after your loan restructuring, you can easily end up in a worse position than when you started. Let us break down the most dangerous psychological and financial traps you must actively avoid.
The Dangerous Habit of Re-Borrowing Against Equity
One of the most heartbreaking pitfalls homeowners fall into is treating their newly unlocked home equity like a free shopping spree. When you lower your rate and free up cash flow, or do a cash-out adjustment, you suddenly have access to thousands of dollars.
If you view that money as extra spending cash for luxury vacations or brand-new cars, you are digging a deeper hole. You are taking long-term housing debt and turning it into short-term consumer trash.
This toxic cycle traps families in perpetual debt, forcing them to repeatedly restart their mortgage timelines just to pay off lifestyle inflation. If you need financial padding for a real emergency, look into safe options like how to get unsecured loans with bad credit instead of continually risking your roof over lifestyle upgrades.
Falling Victim to Predatory Loan Structures
Not every person who offers to lower your mortgage payment has your best interests at heart. The lending world contains predatory actors who look for desperate homeowners drowning in high monthly bills.
These bad actors might pitch you a loan with an artificially low introductory rate that explodes into an unmanageable monster after a few years. They might hide massive balloon payments deep within the fine print of the contract.
Always read every single word of your Closing Disclosure form. If a term looks confusing or too good to be true, walk away immediately.
Protecting your biggest asset requires constant vigilance, much like making sure you avoid the silent DIY solar mistakes that destroy your home insurance payout when updating your property. Never let a smooth-talking salesperson rush you into signing a contract you do not completely understand.
Neglecting Your Credit Health Post-Closing
Many people mistakenly believe that once their mortgage is successfully restructured, their credit score no longer matters for a long time. They stop checking their reports, miss a random credit card payment, or max out their revolving accounts.
This is a massive oversight. Your credit profile dictates your insurance rates, your ability to buy a reliable vehicle, and your financial security.
Maintaining a pristine financial profile requires consistent, boring daily habits. If you start your mornings stressed out and disorganized, it bleeds into your money management, leading to dangerous morning routine mistakes that secretly destroy your daily productivity. Keep your mornings calm, pay your bills on time, and protect your credit score like the valuable asset it truly is.
Your Blueprint for a Better Financial Future
Navigating the complex world of home loans can feel intimidating at first glance, but you now possess the exact tools required to win. By stripping away the scary banking myths, understanding your true closing numbers, and avoiding dangerous financial traps, you are fully in control of your destiny.
Remember that your mortgage is just a tool designed to serve your family's happiness and stability. If your current loan terms are draining your energy and emptying your savings, you have every right to change them.
Take a deep breath, look closely at your current monthly statements, and take that first confident step toward financial relief.
I know how stressful it feels to carry heavy housing debt, but reclaiming your financial freedom is entirely possible when you trust the math. Your future self will thank you for taking action today!
Common Questions About Mortgage Restructuring
Does changing my mortgage loan hurt my credit score long-term?
No, it does not harm your long-term credit health. While a temporary dip might occur due to a hard inquiry during the application, successfully managing a lower monthly payment establishes a stellar, consistent history that boosts your score over time.
Can I restructure my loan if I am self-employed?
Yes, absolutely, though the paperwork requirements are more rigorous. Self-employed borrowers typically need to provide two years of complete tax returns, profit and loss statements, and business bank records to prove steady income to the underwriter.
What is the minimum credit score needed for a better rate?
While guidelines shift constantly across different lenders, many programs accept scores starting around six hundred and twenty. However, securing the most competitive market rates typically requires a score of seven hundred and forty or higher.
How do I know if the monthly savings outweigh the closing costs?
You calculate your break-even point by dividing the total closing costs by your projected monthly savings. If the math shows you will stay in the home long past that break-even month, the restructuring plan is financially sound.
Is it possible to roll my remaining credit card debt into a new loan?
Yes, this is known as a cash-out transaction. It allows you to pay off high-interest revolving debt using your home equity, though it increases your overall mortgage principal balance.
What happens if my home appraisal comes in lower than expected?
A low appraisal can disrupt your loan-to-value ratio, potentially requiring you to bring extra cash to the closing table or pay private mortgage insurance. You have the legal right to challenge the report if you discover factual errors in their local market data.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute official financial, legal, or tax advice. Mortgage guidelines, interest rates, and lending qualifications change frequently and vary widely based on individual circumstances. Always consult directly with a licensed financial advisor or a certified mortgage professional before making any major decisions regarding your personal debt or property. We are not responsible for any financial losses or credit impacts resulting from the interpretation of this general guide.