Dealer Fees You Should Never Pay When Buying a Car (And How to Avoid Them)
Walking into a car dealership finance office without a plan is the easiest way to lose thousands of dollars in hidden markups and junk add-ons. Dealerships make most of their profit not from the sticker price on the windshield, but by quietly inflating your interest rate and rolling unwanted warranties into your monthly payment. In this guide, I will show you how to spot phantom dealer fees on page one, how to stop lenders from marking up your interest rate, and how to negotiate a clean out-the-door price that keeps your monthly budget safe.
📌 What You Must Know Before Signing an Auto Loan:
-
Get pre-approved before you go: An outside financing letter from a credit union strips the dealership of their power to secretly mark up your interest rate.
-
Negotiate the Out-The-Door price only: Never discuss monthly payments; finance managers stretch loan terms to 84 months to hide thousands in expensive fees.
-
Cross off phantom add-ons: Nitrogen tires, fabric sprays, and window etching are high-margin dealer markups—tell them to remove every single one.
-
Check for prepayment penalties: Ensure your contract states "no prepayment penalty" so you can pay extra on your principal balance without getting fined.
Decoding the Paper Mountain of Car Financing
To protect your bank account, you have to understand why a car contract is designed to be so confusing. When you finance a vehicle, the dealership acts as an intermediary between you and various institutional lenders.
They don't just hand you the bank's raw loan offer; they act as a broker who can legally inflate the interest rate and tack on dozens of optional administrative products.
The finance office makes a massive percentage of its total corporate profit not by selling cars, but by selling high-margin financial packaging. If you walk in unprepared, you become an easy target for automated profit margins.
Let us break down the exact sneaky line items that quietly inflate your monthly payment without your explicit consent.
The Silent Danger of Dealer Document Fees
Let us tackle the most common line item on page one of your contract: the documentation fee, often called a doc fee. Dealerships will look you dead in the eye and claim that this is a mandatory government tax or state-regulated filing fee that everyone has to pay.
They make it sound like an unchangeable utility bill, right up there with vehicle registration and sales tax.
This is a complete, highly polished marketing fabrication in many states. While some jurisdictions place strict legal caps on how much a dealer can charge for paperwork, other states leave the doc fee completely unregulated.
Dealerships will quietly insert a five-hundred or eight-hundred-dollar doc fee into your contract, pocketing that cash as pure, unadulterated profit.
When I bought my first truck, I simply nodded along when I saw the doc fee line, assuming it was a mandatory legal requirement. It wasn't until years later that I learned doc fees are often completely negotiable, and dealerships use them to squeeze extra cash out of trusting buyers who don't ask questions.
🎬 Insider Video Guide: 7 Dealership Fees You Should Always Refuse
If you want to know which fees are legally mandatory and which ones are pure dealer profit, take advice from someone who spent over forty years running car dealerships. Watch this straight-talking breakdown from auto veteran Ray Shefska on CarEdge. He reveals the seven exact junk fees you should firmly cross off your contract before signing:
Now that you know which printed fees to challenge on the front page, let us uncover the sneaky physical add-ons finance managers quietly bundle into your monthly payment:
The Phantom Add-On Products
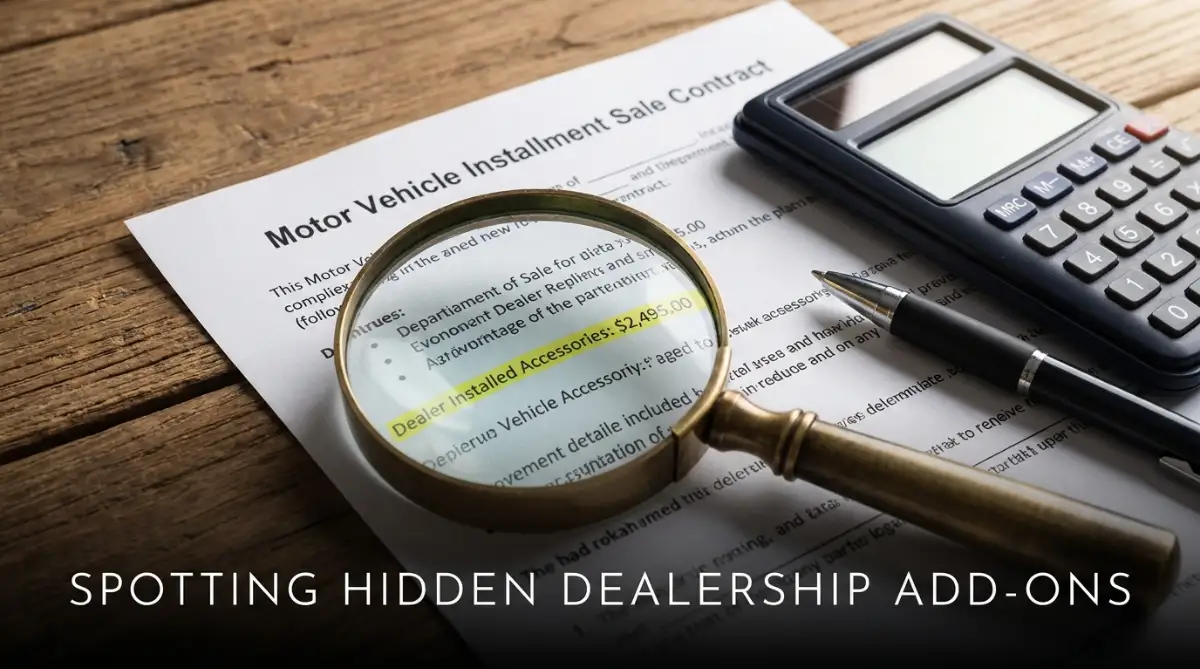
This is where dealerships make their most aggressive profits. As you are sitting there nodding along with the paperwork, the finance manager will often bundle expensive physical or digital products straight into your loan balance without ever asking for your clear permission.
These packages usually include things like "nitrogen-filled tires," "window etching security," "fabric protection spray," or overpriced gap insurance.
They won't ask you, "Would you like to buy this fabric spray for five hundred dollars?" Instead, they will phrase it like a package deal: "I've gone ahead and included our standard protection bundle to keep your new investment safe."
Because the fee is quietly rolled into your total monthly payment spread across sixty or seventy-two months, an extra eight hundred dollars only looks like twelve dollars a month on paper. Your brain ignores it as insignificant noise.
In reality, you are paying heavy interest on a five-hundred-dollar bottle of Scotchgard or basic window stickers for the next six years.
📑 The Dealer Fee Cheat Sheet: Mandatory Government Fees vs. Bogus Dealer Markups
My Negotiation Rule: When reviewing your final sheet, tell the manager: "I gladly pay legal state sales tax, DMV registration, and the vehicle price. I will not pay a single dollar for protection packages, prep charges, or tire air."
The Stealth Interest Rate Markup
This is the most financially devastating hidden fee on the entire page. When you have a solid credit score, a bank might approve you for an auto loan with a clean 5.5% interest rate.
When the finance manager pulls your credit report and sees that approval, do they hand it straight to you? Absolutely not.
They have what the industry calls "dealer reserve." The lender legally allows the dealership to markup that interest rate by one or two percentage points as a reward for bringing them your business.
If the bank said 5.5%, the finance manager will casually tell you, "We got you approved at 7.2%." You assume that is the best the market can offer, so you sign the agreement.
That 1.7% invisible markup doesn't sound like much, but over the course of a five-year loan on a thirty-thousand-dollar car, it quietly steals thousands of dollars straight out of your pocket and hands it directly to the dealership owner.
💸 The True Cost of a 1.5% Interest Rate Markup ($35,000 Loan / 60 Months)
-
Bank's Real Approved Rate (5.5% APR): Monthly Payment =
5,119 -
Dealer's Marked-Up Rate (7.0% APR): Monthly Payment =