The Ceiling Leak That Cost Me Everything
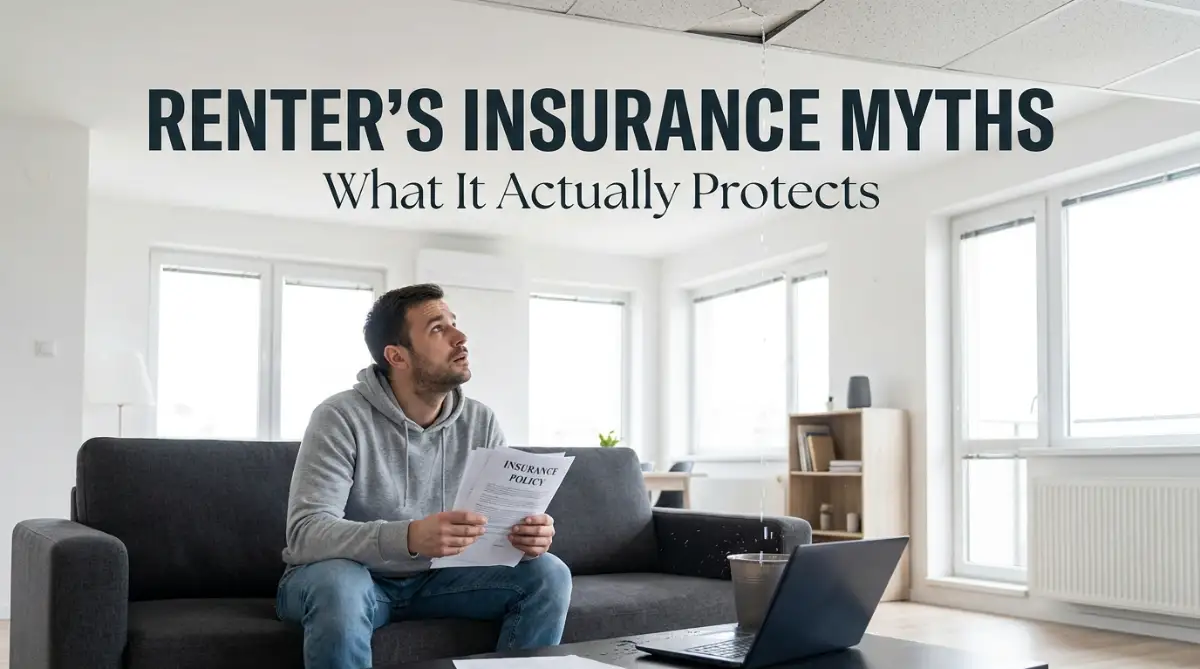
I remember standing in the middle of my living room on a completely random Tuesday afternoon, staring in absolute horror as a steady stream of dirty water poured directly onto my expensive new laptop. The pipe in the apartment above mine had burst while my neighbor was at work. I scrambled to grab towels and move my television, but the damage was already done. My laptop was completely fried, and my customized velvet couch was soaked in rusty water. I honestly felt a tiny bit of relief because I assumed my landlord's massive insurance policy would just write me a check to replace my ruined stuff. When I called the property manager the next morning, he coldly explained that the building's policy only covered the drywall and the actual floorboards.
My personal items were legally considered my own problem. I hung up the phone feeling completely sick to my stomach, realizing I had just lost over three thousand dollars worth of electronics and furniture because I believed a terrible myth.
Have you ever moved into a new apartment, signed the lease, and just assumed you were fully protected by the building owner? It is an incredibly common and extremely dangerous assumption.
Millions of smart, hardworking people skip buying their own rental policy because they genuinely believe the landlord has them covered. They see the fancy lobby and the expensive security gates, and they think their personal belongings are safe inside a corporate bubble.
This specific misunderstanding creates absolute financial devastation for young professionals and families every single year. You work incredibly hard to buy a nice television, a reliable computer, and comfortable furniture.
When a sudden fire, a pipe burst, or a break-in occurs, you expect a safety net to catch you. Finding out that you are entirely on your own while standing in a flooded living room is a completely traumatizing experience. The stress of trying to replace everything out of your own pocket can easily force you to empty your emergency savings or take on massive credit card debt.
We are making huge financial gambles based on terrible advice we heard from friends or misread on internet forums. It is time to clear the air, tear down these expensive myths, and look at exactly how this specific type of protection works in the real world.
Tearing Down the "Landlord Liability" Illusion
To actually protect your bank account, we have to start by completely separating your physical stuff from the physical building. The biggest lie in the housing market is that the property owner is financially responsible for everything that happens inside the walls of your unit.
Your landlord does carry a very heavy, expensive insurance policy. But that policy only protects the physical structure that they actually own.
If the building burns down, the landlord's policy pays to rebuild the roof, the walls, and the plumbing. It does not pay a single dime to replace your burned clothing, your melted television, or your destroyed family heirlooms.
The insurance companies draw a very aggressive line between the structure of the building and the personal property sitting inside of it. If you do not own the building, you cannot insure the building. If the landlord does not own your laptop, they cannot insure your laptop.
This simple separation of ownership is exactly why you need your own dedicated policy. Let us systematically destroy the most common misconceptions people have about what these policies actually do behind the scenes.
Myth 1: "My Stuff Isn't Valuable Enough to Insure"
Whenever I tell my friends they need to buy a policy, the very first excuse they throw at me is always the same. They say, "I just buy cheap furniture from IKEA, and my clothes are old. I don't own any expensive diamond rings or famous paintings, so insurance is a total waste of money."
This is a massive psychological trap. You are heavily underestimating the true replacement cost of your normal, everyday life.
You might not own a Picasso painting, but think about what it would actually cost to buy everything you own again on the exact same day. If a fire destroys your apartment tonight, you have to buy a new bed, new sheets, new towels, a month's worth of work clothes, a television, a laptop, and every single fork and plate in your kitchen.
If you sit down with a calculator and add up the retail price of replacing every single boring, everyday item in your house, the number easily skyrockets past ten thousand dollars.
Renter's insurance is not designed strictly for rich people with expensive jewelry collections. It is designed to prevent a normal working person from going completely bankrupt trying to buy basic underwear and a mattress after a total disaster.
Myth 2: "The Policy Only Covers Things Inside My Apartment"
This is one of the coolest, most highly misunderstood features of a standard policy. Most renters think their coverage stops the exact second they walk out of their front door.
They believe the protection is physically trapped inside the four walls of their specific unit. This is completely false.
Your personal property coverage actually follows you almost everywhere you go in the world. If you travel to a coffee shop downtown and someone steals your expensive laptop right out of your backpack while you are ordering a drink, your policy will usually cover the theft.
If you take a vacation to Europe and your luggage gets stolen from the hotel lobby, your rental policy back home can step in to reimburse you for the stolen clothes and electronics.
I used to carry my expensive camera gear around in a state of constant panic, terrified I would drop it or get robbed on the subway. When I finally read the fine print of my policy, I realized my gear was protected even while I was sitting in a park miles away from my actual apartment. Finding out that my coverage extended to my car and my travels gave me a massive amount of mental peace.
If you want to understand exactly how the claims process works when your items are stolen outside your home, watch this simple breakdown.
Myth 3: "It Only Protects My Physical Stuff"
When we hear the word "insurance," our brains immediately think about broken televisions or stolen bicycles. We focus entirely on physical objects because they are easy to visualize and count.
But the absolute most valuable part of a renter's policy has absolutely nothing to do with your physical stuff. The true power lies in the "Personal Liability" section of the contract.
Imagine you accidentally leave a candle burning in your bedroom, and it starts a fire. The fire spreads and severely damages the apartment next door, completely ruining your neighbor's expensive furniture.
Because you started the fire, your neighbor and the landlord can legally sue you for the massive cost of all those repairs. You could be facing a lawsuit for fifty thousand dollars or more.
If you have a solid rental policy, your personal liability coverage kicks in to fight that battle for you. The insurance company provides the legal defense team and actually pays the settlement money up to your policy limit.
This liability coverage also protects you if someone gets physically hurt inside your apartment. If you throw a party and a guest slips on a wet floor, breaking their arm, your policy covers their medical bills. Without this hidden safety net, a single clumsy accident could result in your wages being legally garnished for the next ten years.
Myth 4: "I Cannot Afford Another Monthly Bill"
We live in a world where everything feels incredibly expensive. Groceries cost more, gas prices are high, and streaming subscriptions quietly drain our bank accounts every month.
When people hear they need to buy an insurance policy, they immediately assume it is going to cost them a hundred dollars a month. They lump it into the same mental category as car insurance or health care premiums.
This assumption is wildly inaccurate. Renter's insurance is actually one of the absolute cheapest financial products you can possibly buy in the modern world.
For a standard apartment, a highly comprehensive policy usually costs somewhere between twelve to twenty dollars a month. That is literally the cost of buying two fancy coffees or a single fast-food meal.
You are getting tens of thousands of dollars in asset protection and massive legal liability coverage for less than fifty cents a day. When you look at the actual math, you realize that you cannot afford not to have it.
Understanding "Actual Cash Value" vs. "Replacement Cost"
If you decide to buy a policy today, you have to watch out for one specific trap hidden in the checkout process. Insurance companies will give you a choice between two different types of payout methods: Actual Cash Value (ACV) or Replacement Cost.
If you do not understand the difference, you will be incredibly angry when you eventually file a claim.
Actual Cash Value means the insurance company will only pay you what your item was worth on the exact day it was destroyed. If you bought a laptop four years ago for a thousand dollars, it is probably only worth two hundred dollars today. The insurance company will hand you a check for two hundred dollars, and you will be completely unable to afford a brand-new computer.
You must always select the "Replacement Cost" option when setting up your policy.
Replacement Cost means the insurance company will pay you exactly what it costs to walk into a store today and buy a brand-new version of that exact same item, regardless of how old your original item was. It costs a few extra dollars a month, but it is the only way to guarantee you can actually rebuild your life after a total loss.
The "Loss of Use" Lifeline
Let us look at another incredible feature that most people completely ignore until a disaster happens. We already established that a fire or a massive pipe burst can destroy your furniture. But what happens to you physically?
If your apartment is heavily damaged by smoke or water, the city inspectors will often declare the unit legally uninhabitable. You are suddenly homeless, and you cannot sleep in your own bed until the landlord finishes major construction, which could take months.
You have to scramble to find a hotel room or sign a short-term lease somewhere else. Paying for a hotel out of pocket for six weeks will completely bankrupt a normal working person.
This is where the "Loss of Use" coverage steps in like a hero.
If a covered disaster forces you out of your apartment, your policy actually pays for your temporary living expenses. They will cover the cost of your hotel room, and they will even reimburse you for the extra money you have to spend eating at restaurants because you no longer have access to a working kitchen.
This specific coverage acts as a massive financial bridge, keeping a roof over your head and food on your table while you wait for your apartment to be safely repaired. It transforms a terrifying, life-altering disaster into a manageable temporary inconvenience.
Advanced Tech Strategies to Transition Safely
Once you fix the basic structure of your resume, you have to mentally prepare for the actual interview process. Corporate hiring managers are not just looking for a specific skill set; they are aggressively hunting for red flags.
They want to know if you can handle working alone in your living room without a supervisor watching your screen. You have to prove that you are highly organized, incredibly disciplined, and technically capable of managing your own daily workflow.
Let us dive into the expert-level strategies that successful career changers use to completely blow away the competition during remote job interviews.
Mastering Asynchronous Communication
In a traditional office, if you have a quick question, you just tap your coworker on the shoulder. Remote work does not function like that.
Modern distributed teams rely heavily on "asynchronous communication." This means you might send a message on Slack at 9 AM, and your manager in a completely different time zone might not reply until 2 PM. You cannot just sit around doing nothing for five hours while you wait.
During your interview, you must explicitly mention how comfortable you are with this exact working style. Give them a real-world example of how you handle roadblocks independently.
Tell them, "If I hit a problem and my manager is offline, I document the exact issue, move on to my next available task, and leave a clear note so we can review it when they log back in." This single sentence proves that you understand remote culture perfectly. According to organizational behavior studies from Stanford Graduate School of Business, employees who demonstrate strong asynchronous habits are promoted significantly faster in remote environments.
Protecting Your Digital Workspace
When you work from home, your internet connection is your absolute lifeline to your paycheck. If your screen constantly freezes during the Zoom interview, the hiring manager will instantly assume your home is not equipped for remote work.
You must guarantee that your home office setup is totally bulletproof.
Do not rely on a weak wireless signal coming from the other side of your house. If you are struggling with dropped calls, you must look into troubleshooting home Wi-Fi dead zones before you ever schedule an interview. Buying a cheap, long ethernet cable and plugging your laptop directly into the router is the easiest way to guarantee perfect video quality.
You also need to demonstrate basic digital hygiene. Make sure your background is clean, your lighting is bright, and your audio is crystal clear.
If you look like you are sitting in a dark, messy bedroom, they will naturally assume your work habits are just as chaotic. Treat your home desk exactly like a professional corporate boardroom.
Leveraging Free Tech Certifications
You do not need a four-year computer science degree, but you absolutely need to prove that you are not afraid of modern software. Most entry-level remote jobs rely heavily on basic tools like Zendesk, Salesforce, Slack, or Google Workspace.
The incredible secret is that almost all of these massive software companies offer completely free, official training courses directly on their websites.
You can spend a single weekend taking the free "Zendesk Customer Service Agent" course online. When you finish, they give you a digital certificate that you can attach directly to your LinkedIn profile.
When a hiring manager sees that you took the initiative to learn their specific software before you even applied for the job, you instantly jump to the top of the resume pile. You just proved that you are a highly motivated self-starter who does not require expensive, time-consuming hand-holding.
Career-Killing Mistakes First-Time Remote Workers Make
Even when you follow the best advice, human desperation often causes us to make incredibly reckless decisions. The absolute desperation to escape a miserable retail or office job can cloud your judgment, pushing you directly into dangerous traps.
I have seen highly intelligent people destroy their personal finances and their professional reputation simply because they ignored the massive red flags hiding in plain sight.
Let us walk through the most devastating mistakes you absolutely must avoid when hunting for your very first remote position.
Falling for the "Check Cashing" Scam
This is arguably the most common and financially destructive trap on the entire internet. You apply for a remote data entry job, and within twenty-four hours, you get an overly enthusiastic email offering you the position.
The "manager" tells you that they are going to mail you a massive physical check for three thousand dollars to buy your home office equipment.
They instruct you to deposit the check into your personal bank account, keep five hundred dollars as a sign-on bonus, and wire the remaining cash to their "approved laptop vendor."
This is a complete, devastating scam.
The physical check they sent you is completely fake, but it takes the bank a few days to figure that out. If you wire the real money out of your account, the bank will eventually reverse the fake check, and you will be held entirely responsible for the missing thousands of dollars.
A legitimate remote company will either ship you a laptop directly from their own IT department, or they will offer you a standard, monthly equipment stipend on your normal paycheck. Never, ever accept a personal check from a stranger on the internet. If you fall into a deep financial hole because of a scam, you might be forced to research how to get unsecured loans with bad credit just to cover your rent. Protect your bank account aggressively.
Ignoring Cybersecurity Basics
When you accept a remote job, you are essentially opening a digital doorway between your personal home network and a massive corporate database. If your personal laptop is full of viruses or weak passwords, you are a massive liability to the company.
Hiring managers will often ask casual questions during the interview to test your basic security knowledge.
If they ask how you manage your online accounts, and you proudly admit that you use the exact same password for everything, they will immediately end the interview process.
You must demonstrate that you understand digital safety. Mention that you use a dedicated password manager and two-factor authentication for all your professional accounts. Avoiding dangerous password management mistakes proves to the company that you are mature enough to handle their sensitive customer data from your living room.
The Illusion of Total Freedom
The biggest lie surrounding remote work is that you can just sit on a beach with a laptop and work whenever you feel like it. While some advanced freelance roles offer that kind of flexibility, entry-level corporate remote jobs require intense, structured discipline.
Many beginners fail their probation period because they completely lose control of their daily schedule.
They start sleeping in late, taking three-hour lunches, and trying to work while watching television. This lack of structure leads directly to missed deadlines and sloppy mistakes.
If you do not set a strict, professional schedule for yourself, the lines between your work life and your personal life will completely blur together. This leads to massive burnout. Setting clear boundaries is the exact same logic behind avoiding dangerous morning routine mistakes. You must actively protect your focus if you want to survive the transition.
Your Action Plan for Remote Success
Breaking into the remote work world without a technical background feels incredibly intimidating, but you now have the exact blueprint to bypass the frustration. By translating your existing offline skills into corporate language and targeting operational roles, you completely level the playing field.
You understand that passing the interview requires proving your deep organizational discipline, not showing off complex coding skills. By actively avoiding the deadly online job scams and protecting your home internet setup, you are fully prepared to land a secure, high-paying position.
Do not let the fear of a complicated job board keep you trapped in a daily commute you absolutely hate. Update your resume tonight, focus heavily on your communication skills, and start networking directly with the people who actually make the hiring decisions.
I used to think remote work was just an impossible dream reserved for software engineers. But the day I finally realized my basic customer service skills were actually highly valuable to tech companies, my entire career trajectory changed overnight. You have the absolute power to design a comfortable, flexible work life starting right now today!
Frequent Questions About Remote Job Hunting
Do I really need a computer science degree to work for a tech company?
Absolutely not. Massive technology companies require thousands of non-technical employees to function. They aggressively hire for customer success, sales development, human resources, and project management roles where communication skills are far more valuable than coding ability.
What is the absolute best website to find legitimate remote jobs?
While massive sites like Indeed have options, you will face significantly less competition on dedicated remote job boards. Websites like FlexJobs, Remote.co, and WeWorkRemotely heavily vet their listings to filter out scams and focus specifically on high-quality, work-from-home positions.
Will a company pay for my home office equipment?
It entirely depends on the specific company. Major corporate employers will typically mail you a fully configured company laptop and a monitor. Smaller startups might operate on a "Bring Your Own Device" (BYOD) policy, where you must use your own personal computer but receive a small monthly stipend for internet costs.
How do I prove I am actually working if nobody is watching me?
Remote companies measure your value based purely on your daily output, not the hours you sit in a chair. If you consistently meet your deadlines, respond to team messages promptly, and resolve customer tickets quickly, the management team knows exactly how hard you are working.
Are remote entry-level jobs mostly just commission-based sales?
No, while there are many remote sales positions, there is a massive market for salaried operational roles. Positions like virtual executive assistants, data entry clerks, and tier-one customer support agents typically offer a guaranteed base salary and standard corporate benefits.
Can I travel the world while working a remote entry-level job?
Usually, no. Most entry-level remote jobs have strict tax and legal requirements that mandate you physically live and work within a specific country or state. While you avoid a daily commute, you must usually remain near your declared home address for legal compliance and stable internet access.
Disclaimer: The information provided in this article is strictly for educational, informational, and career development purposes. The remote job market is highly competitive and rapidly changing. Job availability, salary ranges, and specific corporate hiring requirements vary wildly depending on the industry and global economic conditions. Always perform your own deep, independent research and strictly verify the legitimacy of any company before providing personal information, social security numbers, or banking details during the application process. We are not responsible for any career outcomes, lost wages, or financial damages resulting from interactions with fraudulent job listings or the interpretation of this general guide.