Making extra cash through a delivery app, freelance gig, or digital craft shop feels incredible until tax season rolls around. Many new contractors treat side income as tax-free cash, only to face a massive, unexpected tax bill in the spring. If you earn money outside a traditional W-2 job, the government classifies you as a small business owner—which comes with distinct rules. Let us unpack how independent contractor taxes function and the straightforward habits that keep your hard-earned profits secure.
📌 Quick Summary: Essential Tax Rules for Side Hustlers
- Save 30% Immediately: Transfer nearly a third of every gig payment into a separate bank account to handle income and self-employment taxes.
- Watch the Self-Employment Tax: You are responsible for the full 15.3% FICA contribution that traditional employers usually split with you.
- Track Deductions Systematically: Utilize GPS mileage apps and log home workspace square footage to legally reduce your taxable net income.
- Pay Quarterly if Required: If you anticipate owing more than $1,000 at year-end, submit estimated payments four times a year to bypass IRS underpayment penalties.
Decoding the 1099 Contractor Reality
To completely fix this massive financial leak, we have to change how you look at yourself in the mirror. You are no longer just a regular employee picking up extra shifts. The very second you accept a gig payment, the government officially labels you as an Independent Contractor.
This label is incredibly important because it changes every single rule regarding how your money is processed. As an independent contractor, you do not receive a standard W-2 form at the end of the year. Instead, you will receive a confusing little document called a 1099 form.
A 1099 form is simply a piece of paper that the app company sends to both you and the IRS. It loudly announces exactly how much gross income they paid you during the year.
Because the IRS gets a copy of this form, you cannot simply pretend the income does not exist. If the number on your tax return does not perfectly match the number on the 1099 form they received, their computer system will instantly flag your account for an aggressive audit.
The Hidden Trap of Self-Employment Tax
Most gig workers kind of understand that they have to pay normal income tax on their earnings. But they are completely blindsided by a sneaky second layer called the Self-Employment Tax.
When you work a traditional desk job, you have to pay a specific tax that covers your future Medicare and Social Security. But here is the catch: your boss actually pays for exactly half of that specific bill out of their own corporate pocket.
When you are a gig worker, you do not have a boss. You are the boss. Therefore, the government forces you to pay both the employee half and the employer half of that specific tax.
This self-employment tax is currently a flat 15.3 percent on your net earnings. This massive chunk is charged entirely on top of whatever your normal federal and state income tax brackets are.
Quick Guide: Employee vs. Independent Contractor Tax Split
- W-2 Worker: Employer pays 7.65%, Employee pays 7.65% (FICA split evenly).
- 1099 Contractor: You cover the full 15.3% Self-Employment Tax (12.4% Social Security + 2.9% Medicare).
- The Write-Off Benefit: You can deduct the employer-equivalent portion (50%) of your self-employment tax on your Form 1040 adjusted gross income.
This double-taxation is exactly why side hustle money disappears so incredibly fast if you are not carefully tracking it. If you make ten thousand dollars driving for a delivery app, you could easily owe three thousand dollars or more back to the government just on that side income alone.
If you want to see a clear, visual breakdown of exactly how the IRS calculates your self-employment tax bracket, watch this excellent explanation.
The 30 Percent Rule: Your Financial Shield
Since you now know that a massive chunk of your gig income actually belongs to the government, you have to protect yourself proactively. You cannot wait until April to figure out the math.
The absolute most important habit you can build as a side hustler is the strict "30 Percent Rule."
Every single time a client pays you, or an app deposits money into your checking account, you must immediately move thirty percent of that deposit into a completely separate, untouchable savings account.
Do not leave it in your main checking account. If you leave the tax money sitting next to your grocery money, you will eventually accidentally spend it.
I used to just guess how much I needed to save, and I was always short at the end of the year. I finally opened a separate high-yield savings account at a totally different bank. I named the account "Do Not Touch - IRS Money." Whenever a client paid me one hundred dollars, I immediately transferred thirty dollars into that hidden account.
By the time tax season rolled around, I already had the entire payment sitting there, completely stress-free. In fact, because I saved aggressively, I usually had a few hundred dollars left over after paying the tax bill, which felt like a massive bonus.
Mastering the Art of Quarterly Estimated Payments
If your side hustle is actually doing really well and generating a lot of cash, you are going to trigger another confusing IRS rule. The government does not actually want to wait until April to get their money. They want to be paid throughout the year as you earn it.
If you expect to owe more than one thousand dollars in side hustle taxes for the year, the IRS legally requires you to make "Quarterly Estimated Payments."
This means you have to send them a chunk of your saved tax money four specific times a year: April, June, September, and January.
The IRS Quarterly Estimated Deadlines Calendar:
- Q1 Payment: Due April 15 (covers January 1 – March 31)
- Q2 Payment: Due June 15 (covers April 1 – May 31)
- Q3 Payment: Due September 15 (covers June 1 – August 31)
- Q4 Payment: Due January 15 of the following year (covers September 1 – December 31)
If you ignore these quarterly deadlines and try to pay the entire massive bill all at once the following spring, the IRS will actually hit you with heavy underpayment penalty fees. They literally fine you just for holding onto their money for too long.
You need to put these four specific dates as permanent recurring alarms in your phone calendar. Sending a few hundred dollars every three months is significantly less painful than trying to find four thousand dollars in a single weekend.
Why You Need to Hunt for Deductions
So far, we have only talked about the painful side of gig economy taxes. But being an independent contractor actually unlocks a massive, highly profitable superpower: Business Deductions.
When you work a normal W-2 job, you cannot deduct the cost of driving your personal car to the office. But when you are a gig worker, you are officially running a small business. The government allows you to subtract the cost of running that business directly from your total income before they calculate your tax bill.
If you make ten thousand dollars, but you spent three thousand dollars on legitimate business expenses, you only pay taxes on the remaining seven thousand dollars.
Every single dollar you successfully deduct is a dollar that the government cannot tax. This is how smart freelancers legally keep thousands of dollars in their own pockets every single year.
The Magic of Mileage Tracking
If your side hustle involves driving your car—like delivering food, picking up ride-share passengers, or driving to a client's house to walk their dog—your car is your biggest tax shield.
The IRS gives you two different ways to deduct your vehicle costs. You can either save every single gas receipt, repair bill, and tire replacement invoice for the entire year, or you can use the much easier "Standard Mileage Rate."
Currently, the IRS allows you to deduct a specific cent amount for every single business mile you drive. If you drive five thousand miles for your side hustle, you can instantly wipe a massive chunk of your taxable income right off the books.
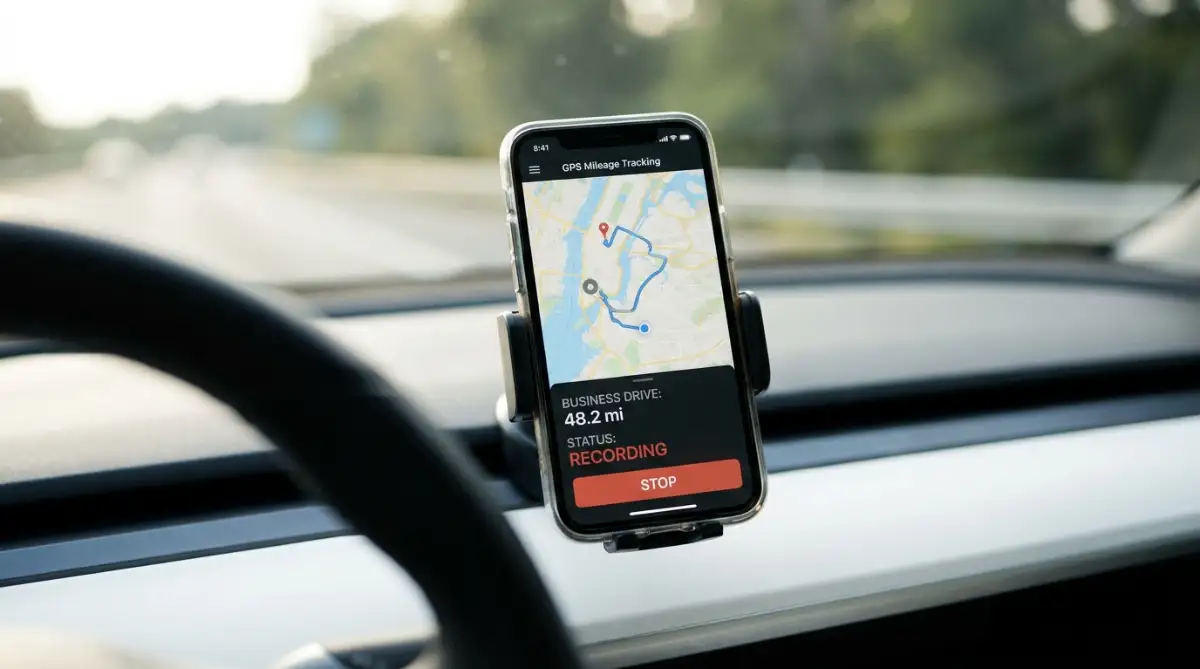
But there is a massive catch. You cannot just guess the miles at the end of the year. If you get audited, the IRS will demand a highly detailed daily logbook proving exactly where you drove and why you drove there.
I used to try keeping a paper notebook in my glovebox, but I always forgot to write down my trips. I lost out on hundreds of dollars in deductions simply because I was lazy.
You need to download an automatic mileage tracking app on your phone immediately. These smart apps use your GPS to track your drives silently in the background. At the end of the week, you simply swipe right for business trips and swipe left for personal trips. At tax time, the app generates a perfect, IRS-compliant spreadsheet that proves every single mile.
The Home Office Loophole
If you do not drive for your side hustle, but instead work from a desk inside your house, you have access to a different, equally powerful deduction. If you are a freelance writer, a graphic designer, or you run an Etsy shop from your spare bedroom, you can claim the Home Office Deduction.
The rule here is very strict, but very profitable. You must have a specific area of your home that is used exclusively and regularly for your gig work.
It cannot be the kitchen table where your kids eat dinner. It must be a dedicated desk or a spare room.
If you meet this rule, you can deduct a percentage of your monthly rent, your internet bill, and your electricity bill based on the square footage of that specific workspace.
If your home office takes up ten percent of your total apartment size, you can legally deduct ten percent of your entire rent from your side hustle income. Over the course of twelve months, that deduction alone can literally save you thousands of dollars in taxes.
Separating Your Financial Lives
One of the most dangerous mistakes a new gig worker makes is treating their personal checking account like a giant mixing bowl.
When you buy groceries, pay for Netflix, buy a new laptop for your freelance work, and pay for business software all out of the exact same checking account, you create a complete accounting nightmare.
When January rolls around, you will be forced to spend hours staring at a messy bank statement, trying to remember if a fifty-dollar charge from six months ago was a personal dinner or a legitimate business lunch with a client.
You will inevitably miss dozens of valuable deductions simply because they are buried under hundreds of personal transactions.
The absolute best professional habit you can develop today is opening a completely free, separate business checking account. You do not need an official LLC to do this; many online banks allow sole proprietors to open dedicated business accounts for free.
Every single penny you earn from your side hustle must go directly into this new business account. Every single business expense—like buying a new camera, paying for software subscriptions, or buying shipping supplies—must be paid using the debit card attached to this account.
When you finally want to pay yourself, you simply transfer a clean chunk of profit from the business account over to your personal checking account.
This aggressive separation makes tax time incredibly easy. You just hand the clean business bank statement to your accountant, and every single transaction on that paper is a guaranteed, provable business deduction.
Mastering Your Financial Strategy Before April Hits
Now that you have a completely separate business checking account, the accounting nightmare is mostly solved. But managing side hustle taxes is not just about keeping your money organized. It is about aggressively playing defense against the IRS rules that naturally work against independent contractors.
You need to establish a set of daily habits that transform tax season from a terrifying, sleep-depriving deadline into a simple, boring chore. The smartest gig workers do not scramble in April. They build a quiet financial machine that works beautifully in the background all year round.
Let us look at a few highly advanced strategies you can implement this week to permanently protect your side hustle profits.
Automate the 30 Percent Rule
We talked earlier about manually moving thirty percent of every single paycheck into a hidden tax savings account. While this is a great start, relying on human discipline is always risky.
If you have a busy week driving deliveries or answering client emails, you will inevitably forget to make the transfer. That one missed transfer can quickly snowball into a massive shortage when tax season arrives.
To fix this, you must rely on modern banking automation. Many online banks now offer smart features that automatically split every incoming deposit for you.
You simply set a rule inside your banking app: "Every time a deposit hits this account, instantly move 30% to the Tax Vault." You never even see the money, so you completely eliminate the temptation to spend it.
Leveraging the Power of Depreciation
This is a professional-level secret that scares most beginners away because the word sounds complicated. But understanding depreciation can legally wipe out a massive chunk of your tax liability.
When you buy a large piece of equipment for your side hustle—like a high-end laptop for coding, a heavy-duty camera for wedding photography, or even specialized tech premium gadgets to test software—you do not always have to deduct the entire cost in one single year.
The IRS allows you to spread the cost of that expensive item over several years. This is called depreciation.
Alternatively, if you need a massive tax break right now, you can use something called Section 179. This specific tax code allows you to write off the entire purchase price of qualifying business equipment in the exact same year you bought it.
If your side hustle made an unexpected five thousand dollar profit this year, buying a new business laptop in December using Section 179 can instantly reduce your taxable profit down to almost zero.
Hiring a Certified Tax Professional
When you first start a side hustle, paying fifty dollars for automated tax software feels like the smart, frugal choice. But as your gig income grows past a few thousand dollars, using basic software becomes incredibly dangerous.
Basic tax software asks you rigid, generic questions. It does not look at your unique business model, and it absolutely will not suggest creative ways to find hidden deductions.
Hiring a certified public accountant (CPA) might cost you a few hundred dollars upfront, but it is an investment that pays for itself ten times over. A good CPA knows exactly how to navigate the massive, confusing IRS tax code.
They will find completely legal deductions you never even knew existed. According to the National Society of Accountants, a qualified tax professional often saves independent contractors significantly more money than their actual billing fee.
More importantly, having a professional sign your tax return provides massive peace of mind. If the IRS ever decides to audit your paperwork, your CPA is legally bound to stand right beside you and defend the numbers they calculated.
Destructive Habits That Will Trigger an IRS Audit
Even when you know the rules, human nature often leads us to make incredibly careless choices. We get lazy, we panic when the bill is too high, or we listen to terrible advice from a friend who claims they know a "secret tax loophole."
The IRS is not a human being you can negotiate with. It is a massive, incredibly powerful computer system designed specifically to flag unusual patterns.
I have watched so many hard-working freelancers completely ruin their financial lives by making silly, avoidable mistakes on their 1099 forms. Let us walk through the most dangerous tax traps you must absolutely avoid if you want to keep the auditors away from your front door.
Mixing Business and Personal Deductions
This is the absolute fastest way to trigger a full, painful IRS audit. When you first realize that business expenses lower your tax bill, the temptation is strong to write off everything you possibly can.
You take your family out to a fancy steakhouse dinner and try to deduct it as a "business meeting." You try to claim your entire monthly cell phone bill, even though you use that phone to text your friends and watch movies ninety percent of the time.
The IRS computer system knows exactly what a normal expense ratio looks like for your specific industry. If you claim that you spent eighty percent of your total gig income on "business meals and entertainment," the system will instantly flag your return for review.
You must be brutally honest. If you use your personal cell phone for your gig work, you can only legally deduct the exact percentage of the bill that applies to business calls.
Failing to Report Cash Tips and Payments
In the world of ride-sharing, food delivery, and private tutoring, clients often hand you physical cash as a tip or payment. Because there is no digital trail for this cash, many gig workers mistakenly believe they do not have to report it to the IRS.
They treat cash tips as invisible money. This is a massive federal crime known as tax evasion.
Even if the app company does not put those cash tips on your official 1099 form, you are still legally required to report every single dollar you earn on your Schedule C tax form.
The IRS conducts random lifestyle audits. If they see that you are paying a two-thousand-dollar mortgage every month, but your official tax return says you only make fifteen thousand dollars a year, they will know you are hiding cash income.
Always deposit your cash tips directly into your business bank account. Keeping your money entirely legal is the only way to sleep peacefully at night.
Waiting Until April to Find Your Receipts
This mistake destroys your mental health more than anything else. You toss every single gas receipt, toll booth ticket, and software invoice into an old shoebox in your closet for twelve straight months.
When April finally arrives, you dump the massive pile of crumpled paper onto your kitchen table and try to make sense of the chaos.
You will inevitably lose important receipts. The ink on thermal paper receipts will completely fade away, leaving you with blank slips of paper that the IRS will absolutely not accept during an audit.
Because you are stressed and rushing to meet the deadline, you will miss out on hundreds of dollars in legitimate deductions.
You need to digitize your receipts immediately. Whenever you buy something for your side hustle, snap a quick photo of the receipt using a free scanner app on your phone.
Upload that digital photo to a secure cloud folder.
Ignoring State and Local Tax Requirements
We spend so much time worrying about the massive federal IRS that we completely forget about our own local government.
Depending on exactly where you live, your state, county, or even your specific city might require you to pay local income taxes on your side hustle profits. Some cities actually require you to purchase a local business license just to operate a freelance graphic design business from your living room sofa.
If you completely ignore these local rules, your city government can hit you with massive fines and aggressively garnish your personal bank accounts.
Always check your local city hall website to understand the exact licensing and tax requirements for independent contractors in your specific zip code. According to the Small Business Administration (SBA), local compliance is just as important as federal compliance for long-term business survival.
Your Action Plan for a Stress-Free Tax Season
Managing the tax implications of your side hustle does not have to feel like a terrifying nightmare. You now understand exactly how the government views your 1099 income, and you have the tools to completely protect your profits.
You are no longer a confused gig worker; you are an educated, prepared independent business owner. By aggressively separating your bank accounts, religiously tracking your business mileage, and setting aside that thirty percent for taxes immediately, you remove all the fear from the process.
Remember that running a side hustle is supposed to give you financial freedom, not endless anxiety. Taking control of your accounting right now ensures that you actually get to keep the money you worked so incredibly hard to earn.
I used to dread the month of April, treating it like a dark storm cloud slowly moving toward my house. But once I implemented these simple organizational habits, tax season actually became a quiet, totally boring week, which is exactly how it should be. You can take absolute control of your financial destiny starting right now today!
Common Questions About Gig Economy Taxes
Do I have to pay taxes if my side hustle makes very little money?
Yes, the rules are very strict. If your net earnings from self-employment are four hundred dollars or more for the entire year, you are legally required to file a tax return and pay self-employment tax.
What exactly is the difference between a W-2 and a 1099 form?
A W-2 is for traditional employees, and the employer automatically takes taxes out of the paycheck before you receive it. A 1099 is for independent contractors, meaning you receive the full gross amount and must calculate and pay the taxes yourself.
Can I deduct my internet bill if I work from home?
You can only deduct the business portion of your internet bill. If you use your home Wi-Fi for your gig work fifty percent of the time, and for watching movies the other fifty percent, you can only legally deduct half of the total bill.
What happens if I completely forget to pay my quarterly estimated taxes?
If you skip your quarterly payments, the IRS will add an underpayment penalty fee to your total tax bill when you finally file in April. The penalty amount depends on how much you owe and exactly how late the payment actually is.
Are the fees I pay to the gig app platform deductible?
Yes, absolutely. If a ride-share company or a freelance marketplace takes a twenty percent commission fee out of your total gross earnings, you can deduct that exact fee as a legitimate cost of doing business on your Schedule C form.
Do I really need to keep physical paper receipts for everything?
No, the IRS legally accepts clear, legible digital copies of your receipts. Taking a picture of your physical receipt with your smartphone and storing it safely in a cloud drive is highly recommended, as thermal paper ink often fades completely over time.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute official financial, legal, or certified tax advice. Tax laws change frequently and vary wildly depending on your specific state, local jurisdiction, and unique business structure. Always consult directly with a Certified Public Accountant (CPA) or a licensed tax professional before making any major decisions regarding your business deductions or tax filings. We are not responsible for any financial penalties, IRS audits, or loss of income resulting from the interpretation of this general guide.